Two stocks sit at the centre of almost every Indian energy conversation this year. One is a state-owned oil producer that earned its highest-ever quarterly pre-tax profit in the June quarter. The other is a private conglomerate whose telecom arm opened the biggest IPO the country has seen this week.
If you are tracking the ONGC share price or the RIL share price, a quick glance at the ticker will not tell you much. The useful part is understanding what sits behind the numbers. This guide covers the latest results, dividends, production trends and the Jio Platforms IPO, then ends with a practical checklist you can use on any stock.
A quick snapshot
| ONGC | Reliance Industries (RIL) | |
|---|---|---|
| What it does | Explores for and produces crude oil and natural gas | Refining and petrochemicals, Jio, retail, new energy |
| Ownership | Government of India holds a majority stake (58.89% as of December 2025) | Promoter-led private company |
| Face value | ₹5 | ₹10 |
| Latest quarter reported | Q1 FY27 (April to June 2026) | Q1 FY27 (April to June 2026) |
| Main earnings driver | Crude oil and gas realisations | Refining margins, Jio and retail together |
| Dividend profile | Higher yield, payouts vary with profits and policy | Low yield, small steady dividend |
| Share price reference | Around ₹236 in mid-September 2026 | Around ₹1,327 in July 2026 |
The price references are snapshots, not live quotes.
ONGC: the business behind the share price
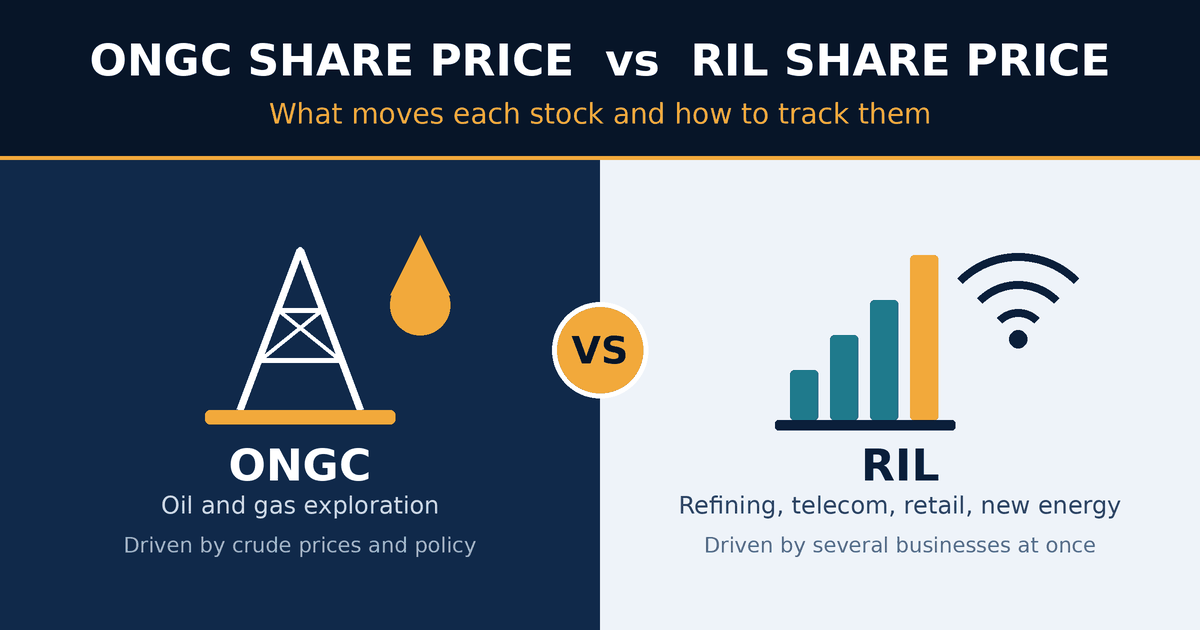
ONGC is India’s largest crude oil and natural gas producer and accounts for roughly 71 percent of domestic output. It earns by pulling hydrocarbons out of the ground and selling them. It also owns stakes in other energy companies, including ONGC Videsh, MRPL and HPCL. That detail matters a lot this year, as you will see below.
The ONGC share price is sensitive to three things: crude prices, government policy and production volumes.
What the Q1 FY27 results showed
ONGC’s June 2026 quarter was striking on a standalone basis:
- Standalone net profit rose 112 percent to ₹17,034 crore, from ₹8,024 crore a year earlier.
- Revenue rose 45.2 percent to ₹46,460 crore.
- Profit before tax hit ₹22,848 crore, the highest in any quarter for the company.
- Net crude realisation climbed to about $99.45 per barrel from $66.13 a year ago.
The reason is simple. ONGC sold roughly the same amount of oil at a much higher price. Production did not rise. Crude output was 4.452 million tonnes against 4.683 million a year earlier, and gas production slipped slightly to 4.756 billion cubic metres.
Why consolidated profit fell while standalone profit doubled
This is the part many articles skip, and it explains a lot of confusion. ONGC’s consolidated net profit fell about 43 percent to ₹6,554 crore. The cause was a large net loss at HPCL, a refining and marketing subsidiary, which reported a loss of ₹12,265 crore in the quarter. Profit attributable to ONGC’s owners still rose around 21 percent to ₹11,899 crore, helped by ONGC Videsh and MRPL.
The lesson: when you read ONGC’s numbers, check whether the article is quoting standalone or consolidated figures. They told very different stories this quarter.
Production is the real long-term question
High crude prices help earnings, but ONGC’s fields are ageing, so output has been flat to slightly down for years. Management has said production should improve as projects progress, including more than ₹40,000 crore of work under way in the Western Offshore, with benefits expected from FY28. Management has also pointed to standalone output of around 39 million tonnes in FY27 and 40 million tonnes in FY28. The company spudded its first deepwater well under the Samudra Manthan exploration push in the Mahanadi basin in July 2026. These are targets, not guarantees, and investors will watch whether they are actually met.
Dividends
ONGC is often seen as an income stock. For FY26, the board recommended a final dividend of ₹1 per share on a ₹5 face value (20 percent), with a record date of 4 September 2026, following approval at the 31 August AGM. Total yearly payouts also depend on interim dividends and profits, so always check the full dividend history rather than one payment.
Reliance Industries: a stock with several engines
Reliance is built differently. Its earnings come from oil-to-chemicals (O2C), the Jio telecom and digital business, Reliance Retail, oil and gas, media and a growing new energy arm. So the RIL share price reflects the combined performance of very different businesses.
What the Q1 FY27 results showed
Reliance reported its highest-ever quarterly revenue, crossing ₹3 lakh crore for the first time, with growth of over 25 percent compared with the same quarter last year. Segment highlights:
- O2C was the largest contributor, with revenue above ₹2 lakh crore on firm refining margins.
- Jio posted an average revenue per user (ARPU) of ₹215.6, up from ₹208.8 a year earlier.
- Retail brought in about ₹90,409 crore, though some analysts pointed to softer consumer demand and margin pressure.
On profit, outlets reported different headline figures, and the year-on-year comparison was distorted because the June 2025 quarter included a large one-time gain from selling listed investments. For exact numbers, use Reliance’s filing on the exchange websites rather than a news summary.
The Jio IPO and why it matters for the RIL share price
The biggest story around Reliance right now is the Jio Platforms IPO. The issue opened for subscription on 21 October 2026, closes on 23 October, and is tentatively expected to list on 28 October. Reports describe it as India’s largest IPO ever, with proceeds mainly meant to repay borrowings of Reliance Jio Infocomm. Before the issue, Reliance held about 66.43 percent of Jio Platforms.
How could this affect Reliance shareholders? There are two views:
- The bullish case: A listing gives Jio a market price, which can make the value inside Reliance more visible, and lower debt at the Jio level strengthens the balance sheet.
- The cautious case: Once a subsidiary is directly investable, the parent can trade at a “holding company discount”, because investors may prefer to buy Jio itself. Analysts raised this concern around Reliance’s earlier AGM.
Nobody knows which view will prevail. It is worth watching the Jio listing price and how RIL reacts around it.
Dividends
Reliance pays a small dividend, recently in the range of ₹5.50 to ₹6 per share, which works out to well under 1 percent of the share price. Investors in RIL generally look for growth, not income.
How crude oil affects each stock differently
Both companies are linked to oil, but not in the same way.
ONGC is a producer. Higher crude prices raise what it earns on every barrel, so its profit moves almost directly with oil.
Reliance is a refiner and converter. It buys crude and sells fuels and chemicals, so what matters is the margin between the two, not the crude price itself. Reliance’s earnings are also cushioned by Jio and retail, which do not depend on oil.
This is why the two stocks can move in opposite directions on the same day.
A practical checklist before you decide
Whichever stock you are researching, go through these steps:
- Read the latest quarterly results, and separate standalone from consolidated numbers.
- Look at the trend over several quarters, not one. Strong quarters can come from one-off factors.
- Check valuation ratios such as P/E and P/B, and compare them with the company’s own history and close peers.
- Review the dividend history across several years, not a single payout.
- Understand the key risk. For ONGC it is crude prices, government policy and falling production. For Reliance it is retail demand, refining margins and how the Jio listing plays out.
- Look at the shareholding pattern for shifts in promoter, institutional and retail holdings.
- Decide your time horizon. A trader and a ten-year investor should look at different things.
You can view live prices, charts and key ratios for the ONGC share price and the RIL share price on Kotak Neo, and cross-check company announcements on the NSE and BSE.
Common mistakes to avoid
- Buying only because a stock “crashed” or “rallied” without checking why.
- Treating a high dividend yield as a guarantee. Yields change when the price or payout changes.
- Ignoring the difference between standalone and consolidated profit.
- Putting all your money into one sector, especially one that moves with a single commodity.
- Acting on tips from social media without reading the actual filing.
Frequently asked questions
Why did ONGC’s profit double while its share price barely moved?
Markets look ahead. A big profit rise caused by temporary high crude prices may already be priced in, and investors also worry about flat production and the consolidated loss from HPCL.
Is ONGC a good dividend stock?
It has traditionally offered a higher yield than most large Indian companies, but payouts depend on profits, crude prices and government decisions. Check several years of history.
Will the Jio IPO increase the RIL share price?
It could improve visibility of Jio’s value, but a holding company discount is a real concern. The outcome is uncertain, so avoid assuming a direction.
Why does Reliance’s profit look different across news reports?
Headline profit can vary based on one-off items, what is included, and how last year’s quarter is compared. The exchange filing is the reliable source.
What are Indian stock market hours?
The NSE and BSE trade from 9:15 AM to 3:30 PM IST, Monday to Friday, excluding exchange holidays.
Which is better, ONGC or RIL?
Neither is better in every case. ONGC is a concentrated bet on oil, gas and policy. Reliance is a diversified bet on energy, telecom and retail. The right choice depends on your goals and risk comfort.
Final thoughts
The ONGC share price is about oil, policy and whether production can finally rise. The RIL share price is about how several large businesses perform together, and how the market values them after the Jio listing. Both are well-known names, but they respond to different forces, and the headline price alone rarely explains why.
Read the filings, compare the trends, and stay clear on your own goals before you invest.
Disclaimer: This article is for information and education only and is not investment advice. Stock prices are subject to market risk. Please do your own research or consult a SEBI-registered advisor before investing.